VZLA max pain, gamma exposure (GEX) & options open interest
As of close · rank #393 by open interest · 250 sessions of history since Sep 30, 2025
VZLA's nearest-expiration max pain is 4.00 for 2026-11-20, net GEX is 4,590,236, its put/call open-interest ratio is 0.26. These are whole-chain derived aggregates as of Oct 16, 2026 close.
VZLA max pain and GEX snapshot
End-of-day snapshot for . Nearest-expiration max pain uses the expiry shown on its card; GEX uses the whole chain. Missing values are unavailable, not zero.
Prices are in US dollars per share. Net GEX is modeled dollar-delta change per $1 underlying move. Max pain minimizes aggregate intrinsic payout for that expiration; it is not a closing-price forecast. Signed GEX uses calls positive and puts negative, a model convention rather than observed dealer inventory. The flip is a confirmed zero crossing; walls locate side-specific concentrations, not guaranteed support or resistance.
Learn how to read the max pain payout example, GEX chart, gamma flip and walls, and open interest versus trading volume.
Advanced options analysis
Public aggregate analysis from the dated chain, normalized where possible for comparison across tickers. Catalyst intensity measures unusual pricing and activity; it does not identify an event, predict direction, or establish that an investment is attractive.
VZLA closed 27.6% below its gamma max of 4.15. It is 10.0% above the delta neutral price of 2.93. Total open interest is 199,052, -11.1% versus the previous session. Its options catalyst-intensity score is 18.4 out of 100. What gamma max means · What delta neutral means
Call versus put open interest changes
Growth compares outstanding contracts on each side. A positive growth gap favors calls; a negative gap favors puts. Standardized surprises compare each measure with its own prior history. These describe the OI balance, not IV skew or buying direction.
| Measure | Value |
|---|---|
| Call OI change, 1 session | -22,018 contracts · -12.2% |
| Put OI change, 1 session | -2,912 contracts · -6.7% |
| Call minus put OI growth, 1 session | -5.5 pp |
| Call OI change, 5 sessions | -20,172 contracts · -11.3% |
| Put OI change, 5 sessions | -3,273 contracts · -7.4% |
| Call minus put OI growth, 5 sessions | -3.9 pp |
| Daily call OI change surprise | -2.22σ (234 prior changes) |
| Daily put OI change surprise | -1.24σ (234 prior changes) |
| Daily call-minus-put growth surprise | -0.79σ (231 prior changes) |
History
Hover for valuesDrag to panScroll to zoomClick a series to hide it ← → step a session+ − zoomTouch: swipe to pan, pinch to zoom, hold for the crosshair
Analysis visualizations
Daily ticker aggregates through 2026-10-16. The max pain curve pools all listed expirations; individual contracts are outside the public dataset.
No matching visualizations.
Aggregate IV history
Chart loads when this section is in view.
Swipe chart sideways to see the full range.
What followed prior gamma-max crosses?
Each historical path starts at 0% on the cross date and follows the close for ten subsequent trading sessions. Cohorts use the same direction as labelled and require gamma max to be within 10% of the close on both crossing sessions.
Crosses below gamma max 4 completed Day +10 paths · latest Sep 28, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 4 | -0.3% | -2.3% to +0.1% | 25% | – | – |
| Day +2 | 4 | -0.4% | -3.8% to +1.4% | 25% | – | – |
| Day +3 | 4 | -6.5% | -11.6% to -1.4% | 0% | – | – |
| Day +4 | 4 | -7.9% | -11.1% to -4.1% | 0% | – | – |
| Day +5 | 4 | -7.0% | -10.4% to -4.5% | 0% | – | – |
| Day +6 | 4 | -7.4% | -8.2% to -5.4% | 0% | – | – |
| Day +7 | 4 | -6.8% | -7.9% to -1.3% | 25% | – | – |
| Day +8 | 4 | -6.1% | -7.3% to -0.8% | 25% | – | – |
| Day +9 | 4 | -5.2% | -6.3% to +0.7% | 25% | – | – |
| Day +10 | 4 | -3.4% | -7.5% to +4.3% | 50% | – | – |
Crosses above gamma max 5 completed Day +10 paths · latest Sep 18, 2026
| Horizon | n | Median | Middle 50% | Above zero | Nominal ≥90% median interval | Confidence floor |
|---|---|---|---|---|---|---|
| Day +1 | 5 | 0.0% | -0.2% to 0.0% | 20% | -6.3% to +0.4% | 0.0% |
| Day +2 | 5 | 0.0% | 0.0% to +0.2% | 40% | -6.8% to +5.4% | 0.0% |
| Day +3 | 5 | -1.0% | -2.2% to 0.0% | 0% | -18.4% to 0.0% | 0.0% |
| Day +4 | 5 | -2.4% | -3.4% to 0.0% | 0% | -16.7% to 0.0% | 0.0% |
| Day +5 | 5 | -1.2% | -3.2% to 0.0% | 0% | -18.9% to 0.0% | 0.0% |
| Day +6 | 5 | -1.6% | -6.4% to 0.0% | 20% | -22.3% to +14.7% | 0.0% |
| Day +7 | 5 | 0.0% | -5.9% to +2.4% | 40% | -15.8% to +13.1% | 0.0% |
| Day +8 | 5 | +3.9% | -7.1% to +14.7% | 60% | -12.9% to +15.8% | 0.0% |
| Day +9 | 5 | +5.7% | -8.1% to +13.1% | 60% | -11.4% to +15.8% | 0.0% |
| Day +10 | 5 | +2.2% | -10.4% to +15.8% | 60% | -11.5% to +15.8% | 0.0% |
Returns are close-to-close after the labelled number of subsequent trading sessions. The confidence floor is the closest-to-zero bound of the order-statistic median interval; it is zero when that interval spans zero. Its coverage is nominally at least 90% under independent observations. Historical paths can overlap, so the interval and floor are descriptive uncertainty guides rather than formal coverage guarantees. Historical, not a forecast.
Last 250 sessions
| Sessions closed above gamma max | 15% |
| Gamma max crosses | 24 |
| Delta neutral crosses | 0 |
| Prior-year sessions closer to gamma max | 90.1% of 233 |
| Prior-year sessions closer to delta neutral | 0.9% of 233 |
| Open interest percentile (1y) | 32th |
| Daily open interest change versus prior year | -2.31σ (-24,930 contracts; 248 prior changes) |
| Open interest change, 5 sessions | -10.5% |
| Open interest change, 21 sessions | -20.1% |
| History available | Sep 30, 2025 → Oct 16, 2026 |
Recent crosses
- closed below gamma max at 3.82 vs 3.93 (-2.8%)
- closed above gamma max at 4.08 vs 3.90 (+4.5%)
- closed below gamma max at 4.09 vs 4.56 (-11.4%)
- closed above gamma max at 4.08 vs 3.87 (+5.1%)
- closed below gamma max at 3.15 vs 3.58 (-13.8%)
- closed above gamma max at 3.07 vs 2.63 (+14.5%)
- closed below gamma max at 3.20 vs 3.90 (-22.0%)
- closed above gamma max at 3.02 vs 2.47 (+18.4%)
- closed below gamma max at 3.13 vs 3.70 (-18.3%)
- closed above gamma max at 3.11 vs 2.60 (+16.4%)
In today's screens
Not in any screen today. See all screens.
Neighbours by open interest
Cite or embed this snapshot
Share the dated 1600×840 image or cite this canonical page. The card contains public derived aggregates, not contract-level quotes.
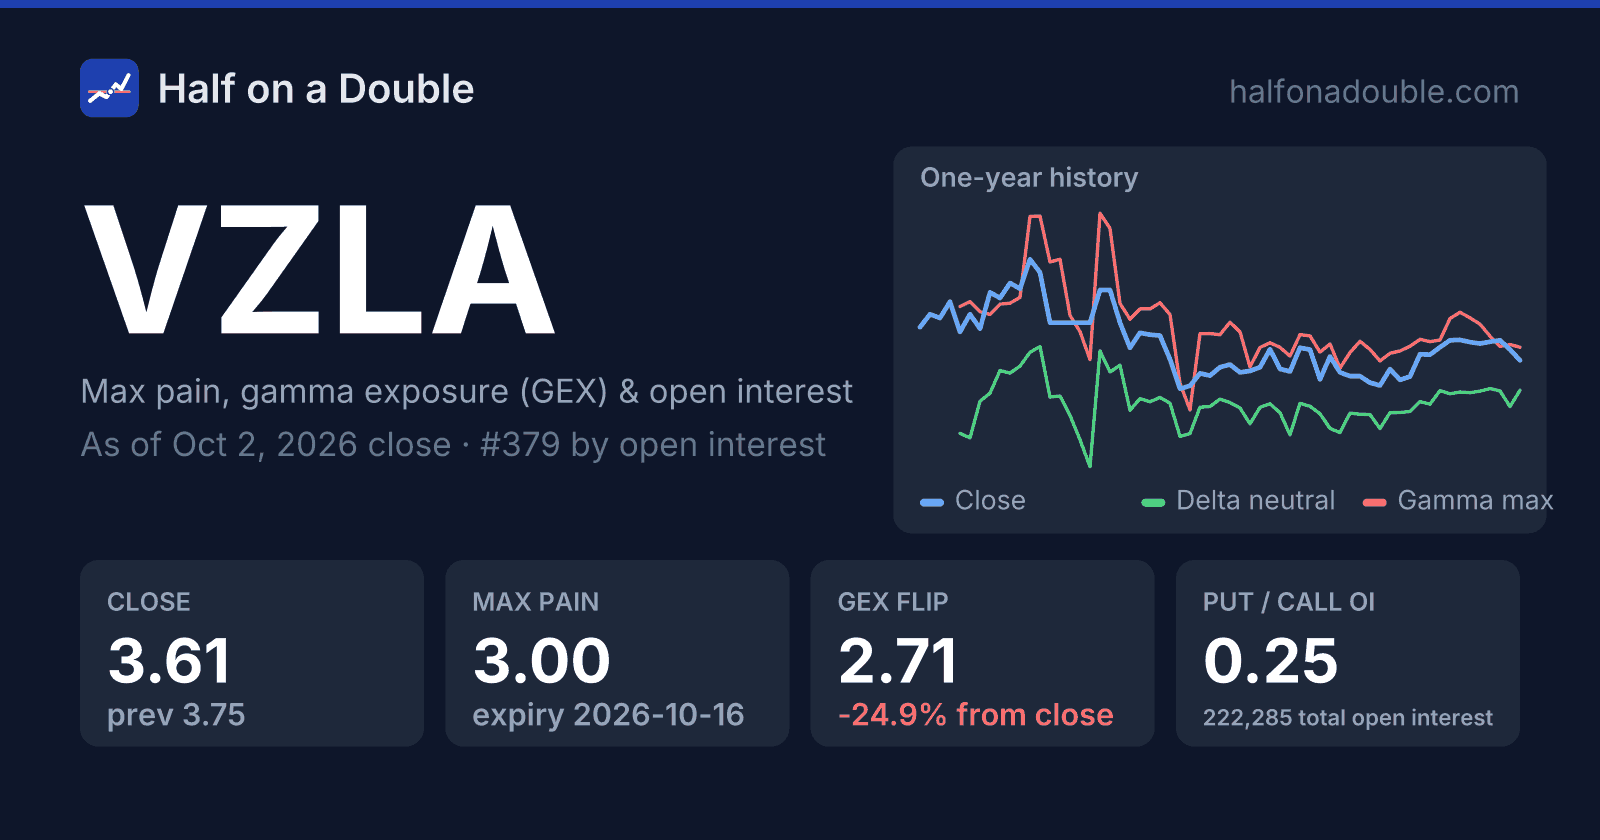
Canonical source: https://halfonadouble.com/stock/VZLA
Questions people ask about VZLA
What is VZLA's max pain for the nearest expiration?
As of Oct 16, 2026 close, nearest-expiration max pain is 4.00 for the 2026-11-20 expiration. It is a payout-minimizing strike for one expiration. An all-expiration pooled value is a different comparison, and neither establishes where the underlying will close. Max pain definition and worked payout example.
Our 2025 max-pain study compares historical Thursday levels with Friday underlying closes and an unchanged-price baseline. Its scope and results are separate from this current ticker snapshot.
What do VZLA's gamma exposure and gamma flip show?
Signed net GEX is 4,590,236 as of Oct 16, 2026 close. No confirmed GEX flip is available; this does not imply a zero exposure level. These aggregate model outputs use calls positive and puts negative. Their sign does not identify dealers' actual positions or predict the next move. How to interpret GEX, gamma flip and walls.
Where is VZLA's gamma max today?
As of Oct 16, 2026, the gamma max for VZLA is 4.15, +27.6% from the 3.25 close. Gamma max is the underlying price at which the summed gamma of every open contract is largest; how it is computed and why it matters.
Is VZLA above or below its delta neutral price?
VZLA closed above delta neutral: 3.25 against a delta neutral price of 2.93. The delta neutral price is where the summed delta of the whole chain is zero; the definition.
How much open interest does VZLA have?
199,052 contracts of open interest across 66 listed contracts on Oct 16, 2026, -11.1% versus the previous session. What open interest measures.
Levels are recomputed after every trading day from licensed end-of-day options data; only derived aggregates are published. Methodology · Data and licence · Not investment advice.